When I first dug into tokenized supplier financing, what grabbed me wasn't the buzzword appeal of blockchain but a practical question: how can mid-market manufacturers actually free up working capital without adding debt or complex renegotiations with banks? The answer, as I’ve learned through conversations with CFOs and fintech founders, lies in tokenization — transforming invoices and payables into digital assets that can be financed more efficiently, transparently, and at lower cost.
What tokenized supplier financing actually means
At its core, tokenized supplier financing takes traditional supply chain finance (SCF) and reimagines it on a distributed ledger. Instead of a paper invoice sitting in an ERP system or being sent to a bank, the invoice becomes a token — a digital representation of that receivable, secured by a smart contract and potentially tradable on a marketplace. That token can be sold to institutional investors, alternative lenders, or even token-based liquidity pools, allowing suppliers to get paid earlier while buyers maintain extended payment terms if desired.
Why this matters for mid-market manufacturers
Mid-market manufacturers often operate on thin margins and long cash conversion cycles. Traditional bank financing can be slow, expensive, and heavily dependent on credit lines that may be seasonal or constrained. Tokenization helps in several concrete ways:
How a typical tokenized financing flow works
I like to break the process down into a straightforward sequence so it stops feeling abstract:
Realistic benefits — what CFOs actually measure
Manufacturers I speak with tend to track a few key metrics when evaluating new finance mechanisms. Tokenized supplier financing can move the needle on:
Who’s building this today and what they offer
Several players are worth watching depending on priorities:
Each approach balances decentralization, regulatory compliance, and counterparty trust differently — choosing the right fit depends on your risk appetite and existing banking relationships.
Key challenges and how to navigate them
Tokenized financing isn’t a silver bullet. I always tell peers to be mindful of:
Practical steps for a mid-market manufacturer to start
From conversations with CFOs who’ve implemented pilots, here’s a pragmatic rollout plan I recommend:
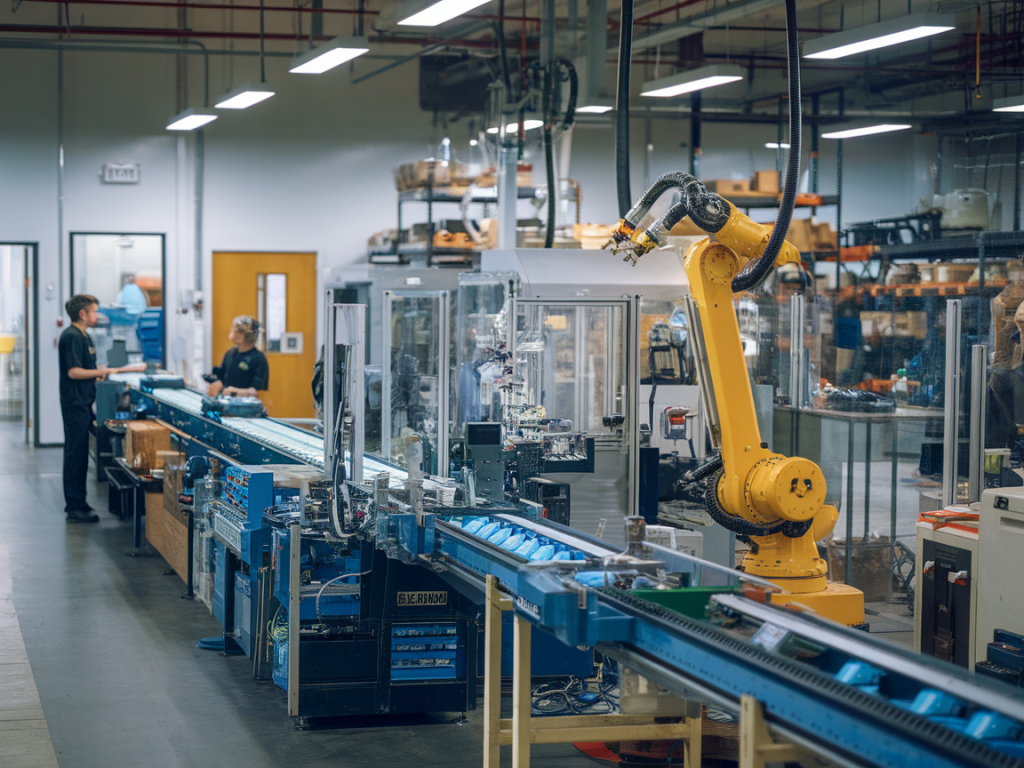
Example scenario: a mid-sized electronics manufacturer
Imagine a manufacturer with 60-day payment terms and a DSO of 70 days. By tokenizing 30% of monthly receivables through a marketplace, they accelerate cash collection on those invoices to 5 days post-issue at an average financing cost 150 basis points lower than their previous factoring rate. The result: freed-up cash reduces the need for a seasonal credit line, lowers interest expense, and allows reinvestment into a critical machine upgrade.
| Metric | Before | After (tokenization of 30% receivables) |
|---|---|---|
| DSO | 70 days | ~60 days |
| Interest expense (annual) | Higher (bank line + factoring) | Lower (marketplace rates) |
| Operational reconciliation effort | Medium | Lower |
Seeing numbers like these is what convinces finance teams to pilot tokenized programs. The trick is to ensure the platform’s legal and operational model aligns with your corporate treasury rules and risk management.
Final thoughts as you evaluate adoption
Tokenized supplier financing blends tech innovation with practical finance. It won’t replace every form of working capital — but for mid-market manufacturers looking to reduce DSO, diversify funding sources, and digitize operations, it’s a compelling tool. Start small, pick partners with proven integrations and investor depth, and treat the first phase as an experiment with measurable KPIs. With the right design, tokenization can turn receivables from static paperwork into dynamic liquidity that fuels growth.